
 Facebook
 X
 Pinterest
 Copy Link

What Experts Forecast for Mortgage Rates and Home Prices in 2027
When it comes to housing, two of the biggest questions on everyone’s mind right now are:
- What’s next for mortgage rates?
- Where will home prices go from here?
And if you’re weighing whether to move in the next few months or wait until 2027, here’s what you should know.
When experts look ahead to 2027, they see a steady housing market. No wild swings. No big surprises. Just a calmer, more balanced market.
And steady makes planning a whole lot easier. Let’s break it down.
Rates Are Expected To Settle into a Steady Range
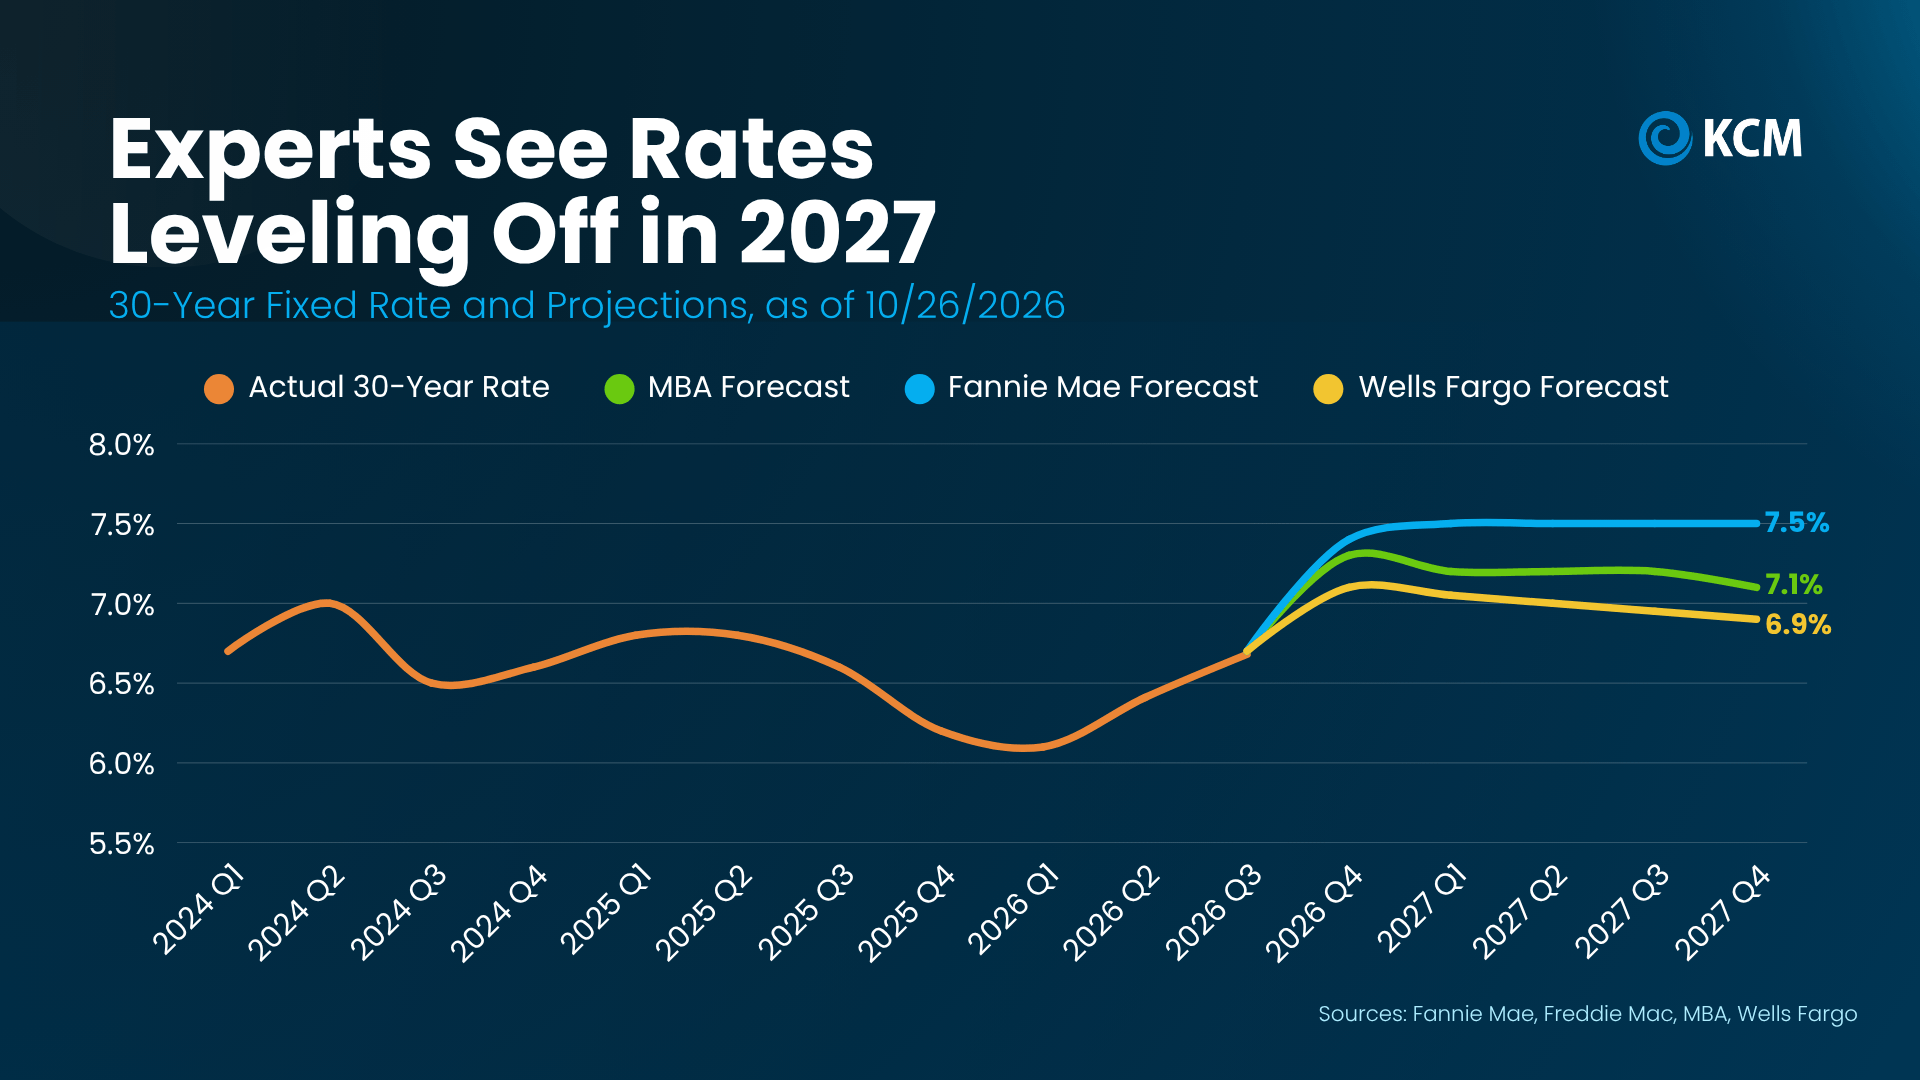
Lots of people are holding out for lower rates. But the latest forecasts from Fannie Mae, the Mortgage Bankers Association (MBA), and Wells Fargo show rates holding fairly flat through 2027 (see graph below):
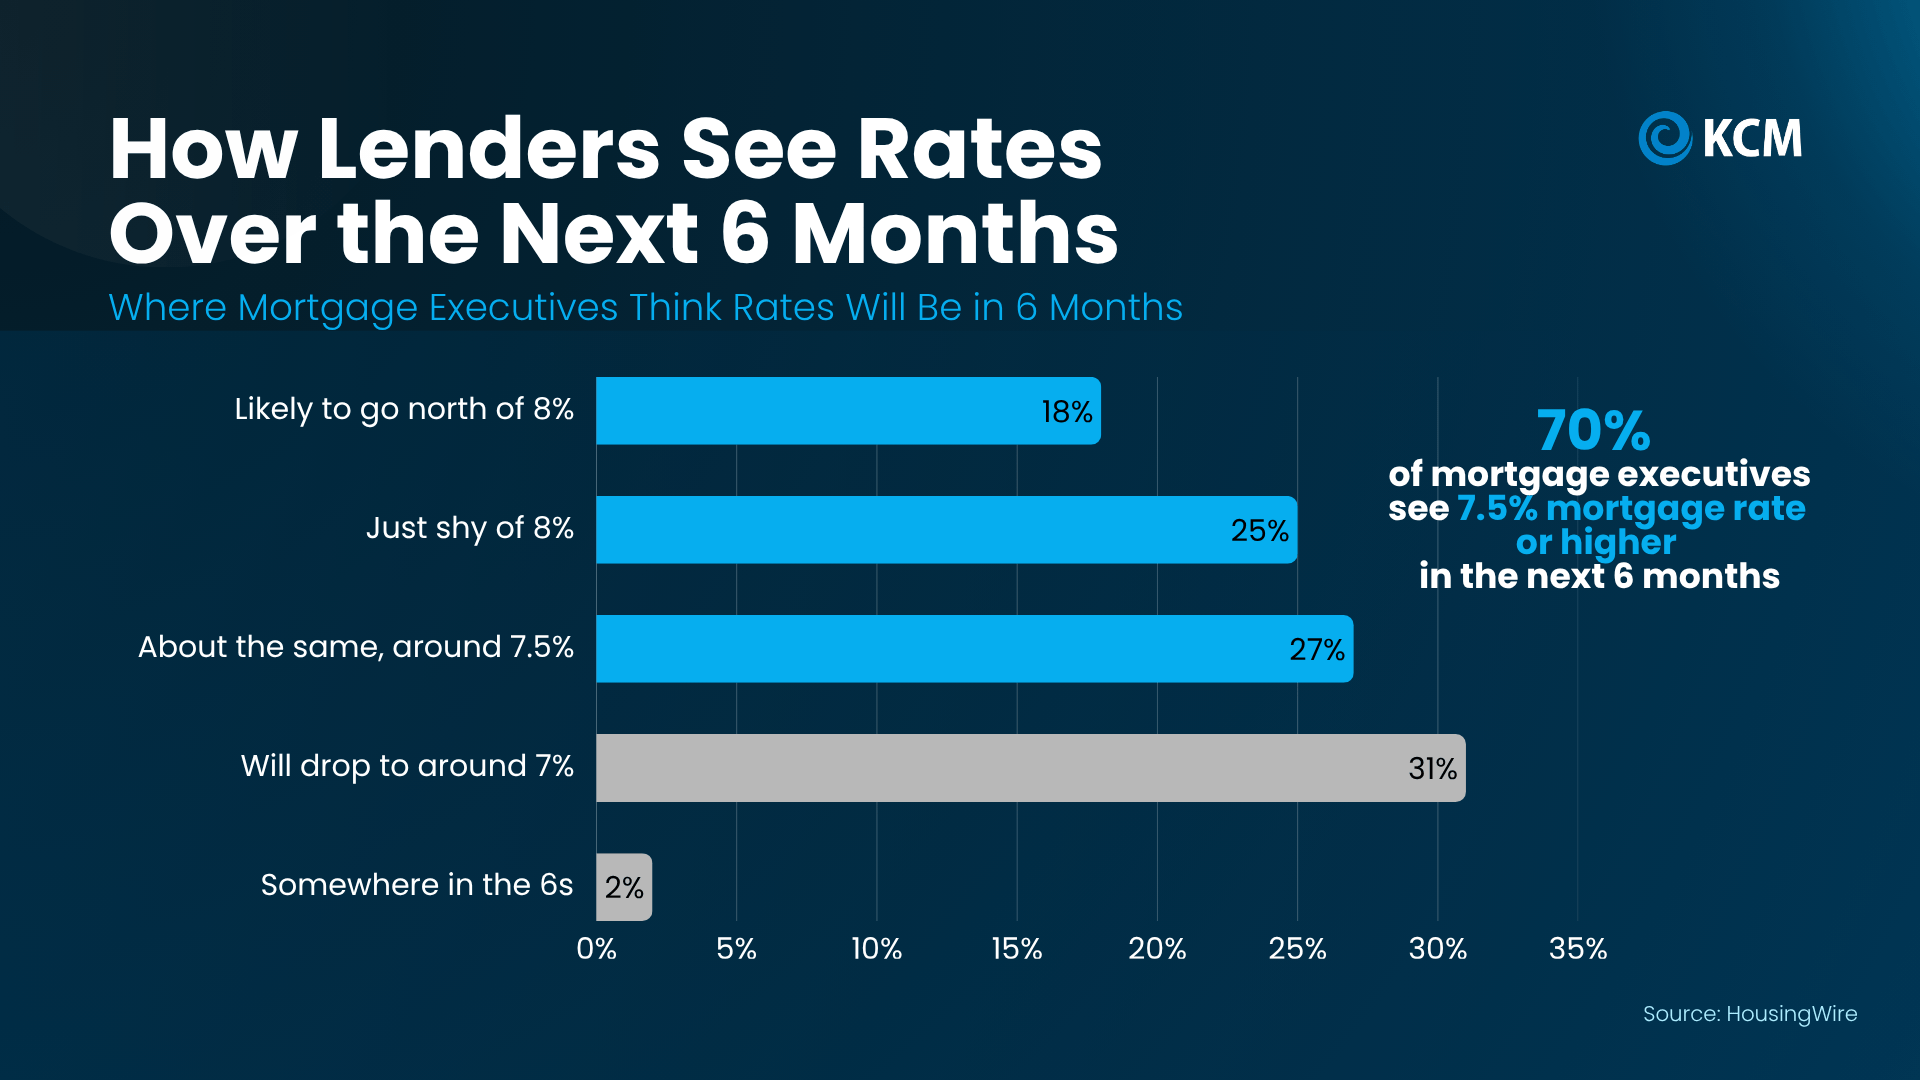
Lenders see it the same way. In a recent survey from HousingWire, 70% of mortgage executives said they expect rates to be around 7.5% or higher six months from now (see graph below):
And if you’re wondering why, the answer is fairly simple. Chen Zhao, Head of Economics Research at Redfin, says:
“Until the underlying economic fundamentals—everything from oil prices to AI–that are keeping rates high change, mortgage rates are unlikely to fall significantly.”
So what does that mean for you? Instead of trying to guess where rates go next, focus on what you can control. Even if rates don’t budge, there are still ways to get the best rate possible. When you talk with your lender, ask about:
- Your credit score. Even a small bump in your score could help lower your rate.
- Different loan types. Some programs offer lower rates or smaller down payments than you might expect.
- Buying down your rate. Paying a little more upfront (called “points”) can lower your rate and your monthly payment.
That way, you’ll know exactly where you stand and what a comfortable monthly payment looks like for you.
Prices Should Keep Climbing, Just More Slowly
But what about prices? Here’s where steady really works in your favor.
Experts don’t see a home price drop coming. On average, forecasts from Fannie Mae, MBA, and Wells Fargo show prices rising about 1% to 1.5% a year through 2027 (see graph below):
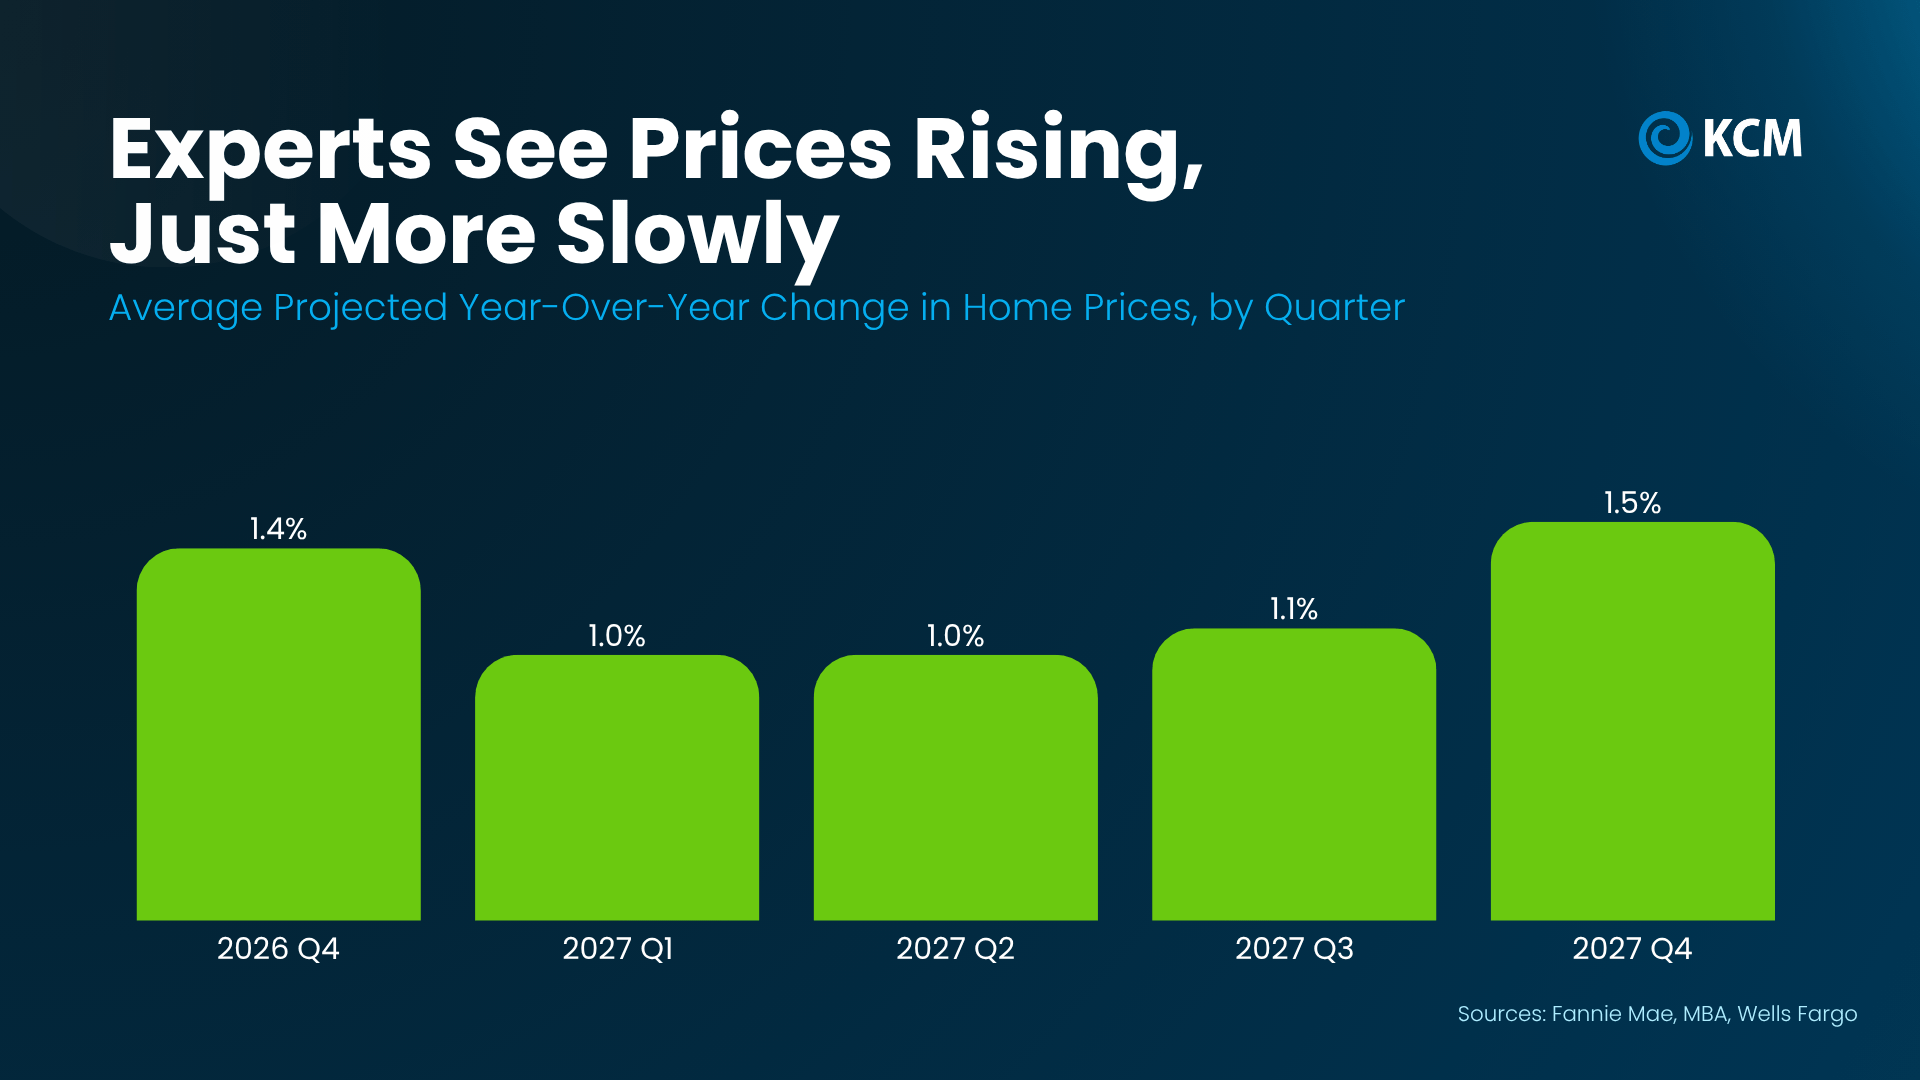
In plain terms, in most places prices are still going up, just not as fast. For sellers, that means your home should hold onto its value. For buyers, slower growth gives you a little more breathing room. Just don’t count on prices getting cheaper while you wait.
But keep in mind, these are national forecasts. Prices can look very different from one area to the next, so what matters most is what’s happening where you live.
The Best Time To Move Is When It Fits Your Life
When the market is steady, you don’t have to try to time it perfectly. There’s no big swing to wait out.
That puts the focus back on you. Maybe you need more space for a growing family. Maybe you’re ready for less upkeep. A steady market makes it easier to plan for either one.
Bottom Line
If you’re asking yourself should you move now or wait? You should know experts see a steady market through 2027, with rates holding near today’s levels and prices rising slowly.
So, rather than waiting for a big shift that may not come, let’s run the numbers on what a move looks like at today’s rates and prices, so you can decide based on your goals instead of the headlines.


 @AgentCindyG
 @AgentCindyG
